Showing posts with label Nissan. Show all posts

Monday, 10 February 2014

Toyota's Profits, Nissan's Lack

One year ago – 2012Q4 that is – Toyota lost money in North America, and made only modest amounts of money in Japan. Today is much different, in contrast to Nissan. Bloomberg nails the source: the yen boom.

Yes, the Japanese economy and the US economy are both doing better, and so therefore should Toyota. But others were profitable in the US in late 2012, and Toyota has not gained market share. My scan of Toyota's financial statements (with glances at those of Ford and GM) suggest the entire gain is due to a more favorable exchange rate. (I have yet to look at the reports of stock analysts to see their take.)

From Toyota's perspective this should be a cautionary tale. They now are rolling in profits, and have the opportunity to continue a restructuring pushed by Akio Toyoda, the firm's near-eponymous chairman. But it does suggest two big problems.

The first is that Toyota is not making substantial money on its North American operations – otherwise it would not have lost money last year. Yes, they have a good market share, but they face competition in key segments and are weak in light trucks (and then there's the failure of their full-sized pickup to gain sales commensurate with investment). Their lack of profits suggests these are major, not minor issues.

Do Toyota's vaunted cost controls no long provide them a competitive advantage?

The second is that Lexus remains their cash cow – which is primarily a US story – but the vehicles themselves come from Japan. When the yen was strong, Lexus lost money. With the weaker yen, that shifted dramatically (though not immediately since Toyota hedges their dollar receipts).

So Toyota needs to improve the bottom line on their US operations. That's surprising, suggesting that their vaunted cost controls are no long providing them a competitive advantage. Second, they need to move away from the yen cost basis on their most profitable products. Otherwise when the yen next strengthens profitability will again collapse. Given that the "cycle time" in the auto industry for realigning what is made where is measured in 4-6 year increments, they had better get moving.

Mike Smitka

Oh, and I did put Nissan in the title, but haven't looked at their financials. But as a quick cut, reverse the above logic: they're not booming because they've successfully aligned their cost base with their revenue base. Instead Nissan's profits will reflect markets strengths, not forex swings.

Wednesday, 1 January 2014

UM LUGAR ÚNICO, UM PARCEIRO ESPECIAL, UM CARRO EXCELENTE E UMA VIAGEM INESQUECÍVEL


Demorei! Sabe por quê? Foi muita coisa ao mesmo tempo. Achei que seria fácil, mas a verdade é que ser multitarefa exige mais do meu processador 4.3 (sou de 1970). Dirigir, definir rotas, fotografar, avaliar o carro, postar no Instagram, observar, aprender, curtir a paisagem, conversar, pensar no post, desfrutar a companhia e mais tudo aquilo que vem junto e ainda organizar isso de uma forma inteligível. Mas como um amigo sempre me diz, é começando que a gente acaba. 

O objetivo principal dessa viagem era ter uma grande satisfação, uma busca por prazer sob diversas formas.

prazer

pra.zer

sm (lat placere) 1 Alegria, contentamento, júbilo. 2 Deleite, gosto, satisfação, sensação agradável. 3 Boa vontade; agrado. 4 Distração, divertimento. 5 Filos Emoção agradável que resulta da atividade satisfeita.


Então começo já dizendo que prazeres novos ou mais complexos não vêm assim tão fácil. Têm que ser conquistados, têm que ser alcançados. E, incrivelmente, o ser humano adora se auto-sabotar e dificultar as aventuras em busca do prazer. Eu mesmo arrumei uma forte dor de garganta na noite anterior. E durante a viagem, antes de chegar até o destino, aquela voz interior que anda sempre com a gente insinuou várias vezes que eu desistisse. Tive que vencer dor, cansaço, preguiça, acomodação e incertezas de um momento pessoal um pouco adverso. E é essa insistência que nos faz sair da zona de conforto.

Para quem ainda não sabe sobre o que estou falando, esse post trata-se da continuação do post "Um lugar, um parceiro, um carro e uma viagem" onde o lugar é a Serra do Rio do Rastro, o parceiro é o meu pai, o carro é um Nissan Altima e a viagem é o prazer que veio de tudo isso.

CONTINUE LENDO >>>

Tuesday, 3 December 2013

NISSAN SKYLINE R34, O MITO JAPONÊS


Nos tempos modernos, a imagem de uma empresa, pessoa ou corporação, é tudo. Fortunas são feitas em cima de imagem. As pessoas lembram das marcas por seus maiores (ou piores) destaques.

Stanley Kubric é o homem do filme "Laranja Mecânica"; Ian Fleming é o pai do James Bond; a Porsche é o reflexo do 911; e a Nissan é a marca do Skyline.

Mas, o que é um Skyline? É o nome usado no Japão para as dinastias dos modelos anteriores do atual GT-R. Hoje pouco vemos o nome Skyline nos produtos correntes da marca, pois a sigla GT-R foi o destaque do carro criado sob o olhar cuidadoso de Carlos Ghosn, para trazer de volta o ícone japonês dos anos oitenta e noventa. E ainda mais, espalhar pelo mundo o poder do Godzilla.

O Nissan GT-R atual nasceu por ordem direta do presidente da empresa. A equipe de projetos deveria entregar um carro que fosse não apenas competitivo, mas referência no mercado. Leia-se “o GT-R tem que acabar com o 911 Turbo, e ser mais barato”.

Nissan GT-R da geração atual

CONTINUE LENDO >>>

Monday, 25 November 2013

UM LUGAR, UM PARCEIRO, UM CARRO E UMA VIAGEM

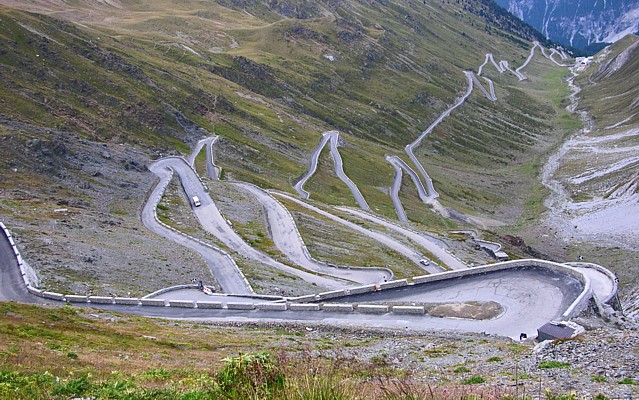
Passo dello Stelvio, a inspiração
Quem aí não gosta de viajar?

Eu trabalho sempre pensando nas próximas férias. Definir um destino para a próxima viagem e fazer os preparativos durante os meses que a antecedem é algo muito prazeroso. Isso é um verdadeiro combustível para a vida, uma esperança, um objetivo, algo que me faz enfrentar o dia-a-dia com mais disposição. 

Esse mundo é tão grande e são tantos os lugares legais que eu gostaria de visitar que já concluí que essa vida não será suficiente. Assim temos sempre que priorizar levando também em conta o tempo de férias e o quanto podemos gastar nas viagens. Eu praticamente posso dizer que trabalho para viajar. Acredito que momentos especiais vividos e sentidos tem muito mais valor que bens materiais. É certo também que alguns destinos são mais difíceis de conciliar com tempo, dinheiro e família. Por exemplo, visitar o Passo dello Stelvio com a família, incluindo uma filha pequena, é um pouco mais difícil que ir para Flórida. 

Mas esse tal de Passo Dello Stelvio já está na minha cabeça faz muito tempo. Desde antes do post do Marco Molazzano logo no início do AUTOentusiastas. Essa passagem talvez seja uma das mais famosas, e aparece em vários programas com vídeos fantásticos ou em matérias com fotos maravilhosas sempre com supercarros fazendo os cotovelos com a traseira escapando. Definitivamente não é uma viagem para ser feita com a família, e por isso ela estava lá, guardadinha em um cantinho especial da minha cabeça (junto com outra para Le Mans), para ser feita em alguma outra oportunidade.

É certo que também, na maioria dos casos, achamos as viagens para outros países bem mais excitantes. Mesmo sendo nativo do país mais bonito do mundo, eu sempre tive tendência a deixar as viagens nacionais para um segundo plano. Estando tudo aí, no "nosso quintal", e com mais facilidade, posso deixar as viagens nacionais para "quando der", como que desprezando o que é mais fácil. Tem outro ponto a favor das viagens internacionais que é a infraestrutura disponível. Parece que é tudo bem mais fácil e seguro. De qualquer jeito, eu não me sinto muito confortável com a minha prática e vivo me questionando isso. Como posso conhecer a Alemanha sem conhecer o Amazonas, que os alemães adorariam conhecer?

Lugar

A matéria que me fez decidir fazer essa viagem
Eis que no comecinho desse ano vi uma matéria numa revista inglesa onde o destino foi o Brazil. Os caras que podem ir ao Passo dello Stelvio com facilidade (e já foram dezenas de vezes), aproveitando que já estavam no Brasil para outro evento, resolveram visitar a Serra do Rio do Rastro em Santa Catarina dirigindo um Audi R8 (que já avaliamos aqui no AE). Por sua vez, essa matéria foi estimulada pela ação da Red Bull com Rhys Milles que subiu a serra fazendo drift com seu Hyundai Genesis em 2010. O vídeo foi muito popular na época.

CONTINUE LENDO >>>

Friday, 11 October 2013

China: all's well ... for now

Today VW claimed sales of 2.35 million units in Jan-Sep. Meanwhile GM's PR machine releases brand sales monthly. I track these, out of curiousity and because I teach a course on the Chinese economy (in which I use Michael Dunne's American Wheels as one of 4 books I ask students to read). GM's 9-month total is ... 2.35 million units.

At one level it seems rather silly for a manufacturer to seek to be the market leader – after all, you can typically boost sales through aggressive discounting, and while a price war is great for consumers and car dealers, it's really, really bad for manufacturers. However, journalists find "who's first" makes good copy, and from a corporate perspective that's free PR. Does it solidify brand image and encourage people to shop your vehicles? Maybe. But whether being first is a good image to create among potential consumers is at base an empirical question, about which I've not the foggiest idea.

it seems rather silly ... to seek to be the market leader

Let's think about this from another perspective. [I round everything – these are back-of-the-envelope calculations.] Given market growth, another 3 months ought to add another 35% and 40% to their annual total – let's call it 6.5 million units between the two. With a total market of perhaps a bit under 20 million this year, and somewhat less if we focus on passenger-oriented vehicles, that comes to a 35% market share.

Now in the hypercompetitive US market Ford and GM, the top two firms, have a combined market share of 34% over the past 12 months. If we expand to the Big Three – GM, Ford and Toyota – their joint share is 48%, down over the past several years. I don't track the Chinese market closely enough to have put together a spreadsheet; my sense is that Ford (story here) is growing its share, while Hyundai and Nissan are strong (and Toyota weak). The purely domestics are much, much smaller though Great Wall with its Haval (web site here, Bloomberg story here) has what is by far the best-selling SUV.

In a market expanding as fast as China's it's possible to preserve margins despite this level of rivalry. First-movers can push down costs and try to build share, thinking of the long run. But in that long run the market will likely have more brands and certainly more manufacturers than either NAFTA or the EU. Once sales slow, profits will plummet towards the global normal, which is such as to make being an assembler barely sustainable.Note 1 [The parts sector is different in that regard, with far few players for many of the major vehicle systems.]

That will be worse news for some, because virtually all production in China is through joint ventures.Note 2 As long as the market is expanding, well, that can be made to work. However, joint ventures are inherently unstable, and when – not if – profits disappear, China will prove no exception. (Indeed, while I know of no breakdown the past few years, in an earlier era Beijing Jeep imploded, and a Peugeot venture stalled. Indeed, an October 14th Bloomberg story notes they may sell a portion of their stake in 3 factories jointly owned with Dongfeng, among other measures designed to raise cash amidst the 6th year of declining sales in the EU.)

It's common to find policymakers thinking of technology as a set of blueprints. In that case, transferring technology is a function of bargaining power. In the real world, however, it's the ability to engineer a car. That is "embodied technology" in the literal sense: it requires building a large team backed by sophisticated management and computer tools for purchasing and other functions. Some firms, notably GM, have chosen to build such capabilities in their ventures, while stressing that the ventures remain independent from either partner. For now GM can use a variety of strategies to increase its own returns – China is part of its global operations, and the vehicles sold in China rely on engineering done elsewhere covered by licensing fees. The longer run though is that it will become more and more a stand-alone operation, paying less in fees to outsiders and even generating some revenue from its own engineering efforts. GM (and SAIC and other partners) will become shareholders, and finesse the underlying tensions of the joint venture structure.

GM [may] finesse the ...tensions of ... joint venture[s]

However, my educated guessNote 3 is that GM has been far more proactive than other ventures. So along with falling profits I predict rising feuds. Chinese government policy in principle promotes fewer players and the pursuit of economies of scale (while in practice proving unable to prevent new entry, most recently through formal permission to allow the domestic assembly of Volvos). There used to be 120 or so domestic makers, but now there are only a few dozen, and some of those exist mainly on paper, selling trivial numbers. Given the instability of joint ventures, though, for some ventures the road ahead will be bumpy and may in fact lead to a dead end. In the coverage I read of the Chinese market, I see an almost single-minded focus on sales and rates of expansion. I read almost no analysis of whether that expansion is taking the right path.

Note 1: for economists, think "monopolistic competition".

Note 2: For general background see China Auto Web. Then there's Automotive News China. Others obviously cover this, such as a nice IBT article. After all, how can you not write about the world's largest car market?

Note 3: I use the phrase "educated guess" very deliberately. I read a lot and strive to integrate that using the analytic skills for which a PhD represents but one step. However, while my Chinese is sufficient for navigating web sites and is improving, my reading speed is still too slow to be a practical research tool – unlike my Japanese and German.

mike smitka

Friday, 7 December 2012

Honda as Japan's Exemplar


...Make where you sell, and that's not Japan...
For a while the impact on the auto industry of 3/11 – the earthquake and tsunami – and then the Thai flood garnered headlines. Lately the headlines in Japan have been politics, politics, and more politics. First there was the US election and the leadership transition in China – Japan's #2 and #1 trading partners. Then there are the upcoming elections in Japan and Korea. These have embroiled the auto industry, too, because of the attempt of various parties in China and Japan to wave the nationalist flag, with much of the fallout hitting bilateral Japan-China auto trade. All this has pushed more mundane news – the transition of the domestic Japanese auto industry – out of the headlines.
So here are two snippets, both using Honda as a foil, though these are more general issues.
First, there's the story – Alan Ohnsman at Bloomberg – that Honda will become a net exporter from the US. Why? – because they're ceasing Accord production in Japan. Of course Nissan is already bringing in the March from its plant in Thailand; Mitsubishi has also begun imports from there. But the yen is cutting into the attractiveness of production in Japan, while the domestic market is small: make where you sell, and that's not Japan.
Second, Honda has now moved into second place in sales for January-November 2012, with 701K units. Meanwhile Nissan, the one-time national champion, ranks fifth. (In third and fourth are Daihatsu and Suzuki; Toyota dominates with 1.55 million units, over twice Honda's level.)
What though is Honda selling? It turns out their success -- and that of Daihatsu [a Toyota subsidiary] and Suzuki -- is due to the growth of the "kei" (minicar) segment, vehicles with engines 360cc or smaller. In the full-size segment Honda is a distant 4th, more-or-less tied with Mitsubishi (29K vs 27K units) but far behind Nissan and Toyota. Indeed, in that segment Honda remains behind the importers BMW and Mercedes (at 32,000 and 33,000, respectively). But in compact cars they were second only to Toyota, and Honda sold enough "kei" to move them to the #2 position.

Passenger Cars


Standard
Small
Mini
Total
Trucks
Buses
Grand Total
Toyota
719,229
700,743
30,549
1,450,521
138,574

1,592,957
Honda
28,598
376,402
264,876
669,876
30,531
-
700,407
Nissan
186,042
224,609
117,382
528,033
91,317
1,460
620,810
Daihatsu
175
2,605
514,912
517,692
117,783
-
635,475
Suzuki
2,469
80,790
416,705
499,964
132,866
-
632,830
Mazda
81,212
61,204
39,253
181,669
24,305
-
205,974
Subaru
92,821
3,957
31,144
127,922
35,623
-
163,545
Mitsubishi
26,534
28,652
45,156
100,342
31,679
-
132,021
Others
181,382
30,867
19
212,268
1,804
64
214,136
TOTAL
1,217,756
1,396,773
1,349,335
3,963,864
663,013
10,399
4,637,276
Now domestic sales – cars, trucks and buses – peaked in 1996 at 7.1 mil units; in 2012, the level will be about 5.4 million units, down almost 25% despite the rebound from the depressed levels of 2011. So no one is doing well, and population aging means a declining number of licensed drivers. Things will not improve. But the mix is becoming bimodal, too. Full-sized cars are fine, quite possibly hitting a new peak of 1.5 million units (triple sales in 1990, during Japan's bubble). The shift is from compact cars to minicars. The former peaked in 1990 at 3.8 million units; 2012 will see sales of 1.6 million units. At the same time, minicars will hit 1.6 million units, up from 0.8 million in 1990. The market is thus split about 1/3rd each, but the shift is one that leaves a less rich product mix.

Full
(share)
Compact
(share)
Mini
(share)
Cars Total
Trucks
1990
467,490
(9%)
3,839,221
(75%)
795,948
(16%)
5,102,659 
3,639,909 
1995
889,260
(20%)
2,654,291
(60%)
900,355
(20%)
4,443,906 
2,403,825 
2000
770,220
(18%)
2,208,387
(52%)
1,281,265
(30%)
4,259,872 
1,686,599 
2005
1,271,349
(27%)
2,089,992
(44%)
1,387,068
(29%)
4,748,409 
1,085,904 
2012 - Nov
1,318,462
(31%)
1,509,829
(35%)
1,459,996
(34%)
4,288,287 
395,377 
...mike smitka...

Saturday, 17 November 2012

...tariffs are 0% on vehicles shipped from Mexico...
Honda is building a full-sized assembly plant (200K units per year) as is Mazda; Nissan is adding a 3rd plant. Part of that is driven by the strength of the yen, at ¥81.3 per US$ on 17 November; the US is the biggest source of profits for the auto industry, so sourcing vehicles for the US market from a non-yen location is important. [The Euro is also strong, to which anyone who has traveled there on a dollar budget can attest. So while VW has operations in Mexico, here I focus on the Japan angle, because I'm teaching a course on the Japanese economy.]
But why Mexico? Logistics costs are high, because most vehicles will likely be exported and because the local supplier base is not as deep as in the US midwest (hence parts must be imported). So while quality is high and wages are competitive, it's not a priori a natural choice.
The answer lies in free trade agreements: Mexico has been more aggressive on that front than the US (and Japan). As a result not only can vehicles be shipped tariff-free to the US–0% from Mexico versus 2.5% on cars and 25% on trucks shipped from Japan. Ditto Europe–tariffs are 0% from Mexico versus 10% on vehicles shipped from the US or Japan. (I have not researched whether Mexico has similar aggreements in Latin America.)
Now Japan could offset some of this were it to negotiate more free trade agreements. (It has one with Mexico.) But that's an awkward process, and has yet to join the biggest pending agreement (TPP, Trans Pacific Partnership). The reason: farmers, whose political clout is disproportionate to their share of the economy, and whose clout over time has led to subsidies and tariffs that allow rice farmers to remain in business despite costs that are multiples of those in other large producers. So removing protection for rice would drive most farmers out of business. In Japan, it's the "3rd rail" of electoral politics.
While we didn't hear anything about the economies of Canada and Mexico, our two biggest strategic partners, in the recent (and unlamented) US political cycle, this movement clearly benefits NAFTA and thus the US. Do higher wages in Mexico harm us? No! And while we might rather have the jobs in the US, we do pick up additional parts business. If we're going to import vehicles – and economies of scale mean that many will still be built in but a single plant globally – then better Mexico or Canada than Japan or Europe!
...mike smitka...

Tuesday, 14 August 2012

The Industry in the face of the Euro's (partial) demise

...Eurxit and beyond...
The Euro as currently configured is not sustainable, from both an economic and from a political perspective. Spain cannot possibly deflate its way back to balance, and 20% overall unemployment and 50% youth unemployment is not politically tolerable. The only way out – forcing German banks to write off their Spanish debt now, matched by stimulus sufficient to turn Germany into a net importer – is not on the policy horizon, though in due course German banks will in fact have to write down debt.
If Spain falls, so will other parts of the Euro zone. Greece of course, and Portugal, and Ireland but not Italy? – I'm not euro-centric and don't know enough to create my own list. I assume France, Spain, Benelux, Austria and Finland will remain. To highlight issues, however, it is sufficient to focus on Spain.
The Euro exit process – I've seen the term "Grexit" used for the likely initial case – is not clear-cut. I would hope that central bankers and pan-European financial institutions are (quietly) working on possible scenarios. If so, in our leak-prone world, they really have been quiet. At the moment, a sensible assumption might be a three years of chaos in those exiting, since there seems to be no planning to support a quick and clean break (cf. the 1997 Asian Financial Crisis). In the interim, those remaining on the Euro would face a corresponding period of deep recession. Then would come two years of recovery that would leave economies below peak, followed by an era of more gradual reconstruction. The total: five lean years, less than what drove Israel to Egypt, but potentially just as devastating to the European heartland.
Not all auto firms are equal. For several – Fiat, Peugeot and Renault – Europe dominates their operations. So far VW appears exceptional, because its German sales base has escaped the current crisis and it is larger outside Europe. Then there are BMW and Mercedes, in the upper segment of the market, about which I know little, and so will hazard no guesses.
Other firms have a footprint in Europe, but are not dominated by what happens there: Fordwerke and Opel are but one part of the global operations of Ford and GM. Europe is peripheral for Toyota, Nissan, Honda and Hyundai. Their parent companies may or may not decide to tough things out – GM will have the hardest time –but unlike Euro-centric firms they have the option of exiting. That would matter if both Ford and Opel/GM leave the market, but otherwise would not remove enough capacity to change the equation.
Then there are automotive suppliers, the larger of which have substantial bases in the Americas and Asia, but still have their core in the Euro zone. My sense from visiting suppliers on a regular basis is that they've done a good job of geographic rebalance, to the benefit of firms headquartered in Europe and the detriment of those headquartered in the US. Asian suppliers are on average relatively weaker in Europe, and so will be less affected. Catastrophic failure of any of the large European suppliers would be catastrophic to the industry, the equivalent of Lehman Brothers in the financial world. Renault would (quietly) cheer the failure of PSA or Opel. All would lose in a meltdown of the supplier base.
Shifting gears from firms to geography, Eurxit (pardon the neologism) would bring a large devaluation to Spain. That is most obvious relative to the Euro; imports from Germany and France [Grance? Framany? – the new Europe will need new jargon] would be much more expensive. However, I would also expect the (new) peso to depreciate relative to currencies in peripheral Europe, since Hungary, the UK, Russia and Turkey already reflect a more sustainable level relative to the Euro.
If it could avoid collapse during the transition, Seat as a local firm (albeit also a VW subsidiary) would benefit from a large shift in relative prices that would improve its strategic position. It could become a true value brand in Europe, with increased exports and (due to the higher cost of imports) would have a near-unassailable position in its home market. Seat might still be Skoda's poorer brother, but its place in the VW family would be more secure. Now the labor cost component of local [Spanish] assembly is modest, and many parts and components are imported, muting the initial benefit. Over the space of a few years, however, local content would rise and with it the peso component of the cost base.
In contrast, firms remaining in the Euro cost base would see their export markets shrink, and the burden of the zone's excess capacity is already heavy. Who has deep pockets? VW, yes, but (potentially) Ford, Opel, Toyota, Nissan, Honda and Hyundai. Chrysler isn't big enough to fully balance Fiat, nor Nissan to balance Renault. Absent government intervention, it is hard to imagine all of these small firms surviving five lean years. In addition, GM's pockets aren't deep; Ford is still rebuilding its balance sheet. Eurxit won't help the US economy and it won't help China, so won't help either firm. So it is conceivable that one of them would exit. It is almost inevitable that the European market would witness multiple bailouts, given a greater political sensitivity to unemployment than in the US. This would be to the detriment of VW, and to any of the branch operations of US and Asian-based firms that remain.
This is my first pass at the implications of Eurxit. Additional differentiation would come from breaking down market shares of individual firms between Eurxit and Euro countries; who is strong in the Mediterranean periphery, and hence more vulnerable? Who has the weakest balance sheet among OEMs and among suppliers? On which side of the divide will Italy lie? Who has a stronger base in the non-euro periphery (Turkey, Hungary, Poland, Russia) and so may be better positioned to pick up pieces of the market via exports?
We can always hope for a miracle European unity, that France and Germany can act as one. So far the fear factor is failing to force fraternity. The initial Eurxit – Grexit? – may change that, but my hunch is that by the time it will be too late.
Finally, this places a fundamental strategic choice in front of firms not irrevocably committed to Europe: do you marshal resources for a long and expensive slog there, or do you prepare to retreat and instead concentrate on the Western Hemisphere and Asia? Even with a reconfigured "euro" divide Europe will remain on average prosperous, and with a population larger than the US will remain potentially profitable. But is every current participant willing to wait until 2018 to realize that potential?
...Mike Smitka...

Thursday, 24 May 2012

Reverse Import Deja Vu?

...a strong yen should boost exports to Japan...
In 1992 I wrote a paper about Japanese car imports, later picked up by the Economist, in Japanese by Toyo Keizai (東洋経済) and by the MIT International Motor Vehicle Program about the growth of Japanese car imports. Ah, but what news was in that? Well, I was writing about "reverse" imports by Japanese of their cars from the US to Japan, alongside the sales of German firms, the only foreign companies to set up proper dealership networks and import processing infrastructure. The recent strength of the yen against the US dollar and particularly against the Euro, made me wonder if we will see a return to that era.
A headline in the May 24th Sankei Shinbun web site thus caught my eye: Mercedes-Benz will sell the "Smart for Two" for ¥1.59 million (US$19,992; €15,950), about a 14% reduction in price. Other forthcoming models of M-B and BMW will likewise carry lower sticker prices or add a lot of options without raising the price. Now the article doesn't make it clear whether the base is appropriate -- it uses year-on-year comparisons, and in general spring 2011 was not a normal time. Still, it cites rises of 37% for M-B and 27% for BMW.
I've only glanced quickly through recent data: given the volatility of the global economy in general, and the post-3/11 economy of Japan in particular, I was expecting to find the data too noisy to interpret. That's not the case.
First, overall imports are at the highest level in the years for which I have (FY1999 to present), even though at 4.0 million cars FY2011 sales are 10% below their mid-2000s level (and 20% below the 5.1 million unit sales peak at the top of Japan's bubble in 1990).
Second, while the German firms are doing OK, both BMW and Mercedes are down from 2007 and the onset of the global recession; only VW and Audi show signs of a sustained increase. What really is driving the increase is Nissan, which now accounts for about 17% of imports or 50,000 units. This is surely consequent to their moving the production of certain vehicles (such as the March) entirely out of Japan.
Still, total imports of 295,000 units remain rather short of the 393,000 level of 1996. While the Japanese media may be full of hand-wringing about the impact of the yen, the evidence so far is modest, when looked at through the lens of vehicle imports. Realistically, it's probably too soon to tell; vehicle sales strategies are penciled in a couple years in advance. We aren't seeing "reverse imports" of Japanese-brand cars from the US -- yet. So from that perspective we're also not back in 1996, when 85,000 Toyotas and Hondas went westward across the Pacific. But it is worth watching.
Source: 「159万円のベンツ 円高追い風、価格抑え輸入車加速」 which freely translated says "Fanned on by the strong yen, a Benz at ¥1.59 million will accelerate imports." From sankei.jp.msn.com of 25 May 2012.
...Mike Smitka...